“Any scientific statement is objective only to the extent that it has mathematics in it.”
Algorithmic Sciences researches, builds and reviews the systems that quantitative trading depends on: the procedures that decide whether a strategy is real, the infrastructure that tests it, the portfolio it joins, the orders that carry it to market, and the controls that watch it once it trades.
We started as a trading research firm, and the work for clients grew out of that. The standard did not change: an idea is treated as wrong until data it has never seen says otherwise, and a simpler system is preferred to a cleverer one that is harder to check.
The methods do not depend on the asset. We work with equities, futures, currencies, options, rates and crypto assets, from daily bars down to tick and order book data.
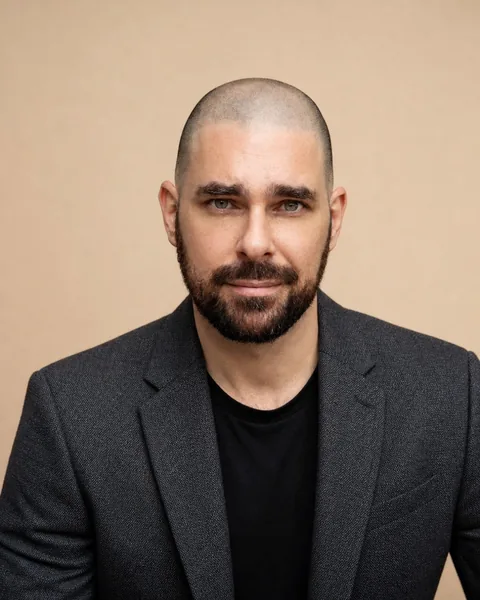
Ben Racz
Founder, Managing Director and Head of Quantitative Research
Ben Racz founded Algorithmic Sciences in 2017 and leads it as Managing Director and Head of Quantitative Research. He designed and tested the firm’s three institutional validation procedures for algorithmic trading systems, and built and led its global team of 21 scientists, engineers and consultants.
The firm’s systems under his lead include an automated risk management system, based on statistics and behavioural analysis, for a US proprietary trading firm and CTA with 35,000 live accounts; a spread prediction model that cut spread costs by 80 to 90% on buy-side currency execution; a distributed backtesting grid that runs 2 million backtests per hour on each server, on commodity hardware and without GPUs; and an execution stack that runs more than 100,000 strategies at once across several venues, with a 7 microsecond critical path from new tick to order on 28 instruments, A/B books, netting, data aggregation and an internal matching engine.
From 2023 to 2025 he was Professor of the Practice in Quantitative Finance and Algorithmic Trading at the College of Engineering of Carnegie Mellon University. He designed and taught two courses, Advanced Financial Quantitative Analysis and Algorithmic Trading, to undergraduate and master’s students from Computer Science, Statistics and Data Science, and the Master of Science in Computational Finance at the Tepper School of Business. His faculty page and syllabus are online.
In 2023 he co-founded the Institute of Algorithmic Trading and Applied Computational Finance and wrote its curriculum: 52 courses and 15 credential programmes, from Python research infrastructure to risk management and execution. He is one of the contributing authors of Humanity’s Last Exam, a benchmark of expert-written questions for measuring the reasoning of AI systems, published in Nature in 2026.
He has managed complex software projects since 2001. Before Algorithmic Sciences he ran an information security consultancy for ten years, from 2006 to 2016: security auditing, ISO 27001 and SOC compliance, PCI-DSS requirements, Linux kernel audits and vulnerability assessments, including service as Director of Security at a NASDAQ-listed company. He also built a data-science-led wholesale trading business that used predictive analytics to find mispriced goods in secondary markets in 27 countries.